

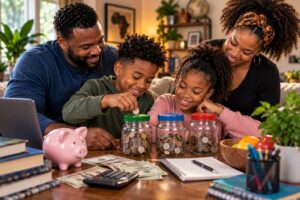

How Allowances Can Teach Children Money Skills Across The Black Community.
An allowance can be more than spending money. When used with guidance, it can become one of the simplest ways to teach children how money works. A small amount given regularly can help a child learn how to save, spend, wait, plan, give, and make decisions. These lessons can be far more meaningful when children are learning with real money instead of only hearing adults talk about finances. Across the Black community, many families want children to grow up with stronger financial skills than previous generations may have received. Some adults learned about money through trial and error. Others may not have had open conversations about budgets, savings, credit, or planning when they were young. An allowance can give families a low-pressure way to begin those lessons earlier. There is no single correct allowance system. Some families connect allowance to chores. Others believe children should complete basic household responsibilities because they are part of the family and use allowance separately for learning money skills. Some families cannot provide a regular allowance but may use birthday money, small earnings, or occasional paid jobs instead. The amount matters less than the lesson. The goal is not to make children obsessed with money. It is to help them understand that money requires choices. If they spend everything today, they may not have enough for something they want tomorrow. If they save steadily, small amounts can grow. If they give some away, they learn generosity. If they make a poor purchase, they can learn from it while the stakes are still small. 1. Allowances Make Money Feel Real. Children often see adults swipe cards, tap phones, order online, or use digital payments without understanding where the money comes from. To a young child, it may seem as if buying something only requires pressing a button. An allowance helps make money more concrete. When children receive a limited amount, they quickly learn that money runs out. If they have ten dollars and spend eight, only two remain. That simple experience teaches more than a long explanation about budgeting. Parents can help children count their money and talk about choices. “You can buy this today, or you can keep saving for the larger thing you wanted.” The decision belongs partly to the child, which makes the lesson stronger. Money becomes easier to understand when children can see, hold, track, and manage it themselves. 2. Saving Teaches Patience. One of the most valuable lessons an allowance can teach is waiting. Children naturally want things now. Saving shows them that larger goals often require patience. A child may want a new toy, game, pair of shoes, book, or special activity. Instead of buying it immediately, families can help the child create a savings goal. If something costs forty dollars and the child saves five dollars each week, they can see progress. A chart, envelope, jar, or savings account can make that progress visible. Reaching the goal can build confidence. The child learns, “I wanted something, made a plan, waited, and reached it.” That feeling can encourage stronger money habits later. Patience learned through saving can also carry into school, work, relationships, and other goals. 3. Spending Choices Teach Consequences. Children will sometimes spend money badly. That is part of learning. A child may buy a toy that breaks quickly, spend all their money on snacks, or purchase something they stop caring about the next day. Parents may be tempted to immediately replace the money or prevent every poor decision. Small mistakes can be useful teachers. If the purchase is safe and reasonable, allowing the child to experience the result can help them think more carefully next time. A parent can ask, “Do you feel like that was worth your money?” rather than shaming them. The goal is reflection. It is better to learn from a ten-dollar mistake at age ten than a much larger financial mistake in adulthood. 4. Families Can Teach Saving, Spending, And Giving. A simple allowance system can divide money into categories. Many families use three basic ones: save, spend, and give. The spending portion can be used for small wants. The savings portion goes toward larger goals. The giving portion can support church, charity, relatives, community causes, or someone in need depending on family values. The percentages do not need to be complicated. Younger children may simply put a small amount into each jar or envelope. This system teaches that money has different purposes. It is not only for immediate consumption. Children learn that they can enjoy money, prepare for the future, and use some of what they have to help others. 5. Allowances Can Teach Basic Budgeting. Budgeting means deciding where money should go before spending it. An allowance gives children a simple way to practice. A child who receives twenty dollars might decide to spend five, save ten, and keep five for a future activity. An older teen may need to budget transportation, lunch, clothing, entertainment, and savings from a larger amount. Parents can guide without controlling every decision. A simple written budget can help older children. Income goes at the top, followed by categories for saving and spending. This makes the numbers visible. Budgeting teaches that every dollar has limits. Choosing one thing often means giving up another. That is one of the most important financial lessons a young person can learn. 6. Allowances Can Create Better Family Money Conversations. Many adults grew up in homes where money was rarely discussed. Children may have heard “We cannot afford that,” but not learned why families make financial choices. An allowance gives parents an easy starting point for money conversations. A child may ask why their money is gone, why saving takes so long, or why two similar products have different prices. These questions open opportunities to discuss value, planning, and tradeoffs. Older children can gradually learn more about how households work. Parents may explain that families pay for housing, food, utilities, transportation, insurance, and other needs before spending on extras. Children