

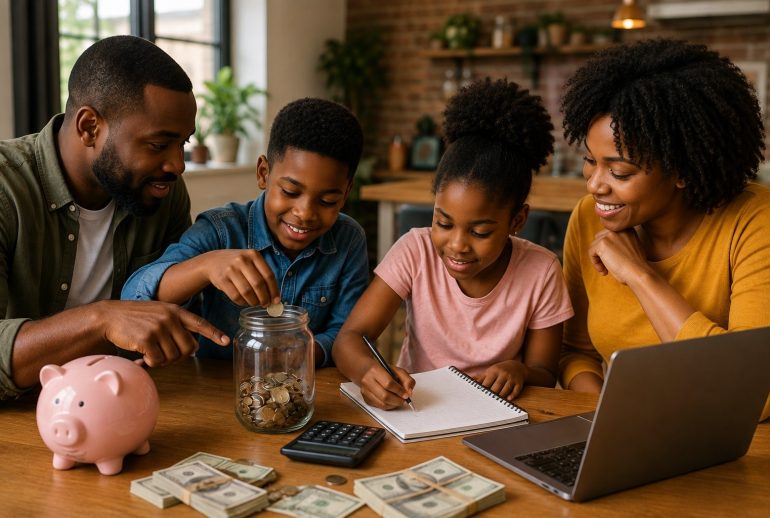
Financial literacy is one of the most important life skills young people can learn. Children and teens may not have full financial responsibilities yet, but they are already forming ideas about money. They watch how adults spend, save, budget, borrow, give, worry, plan, and talk about finances. They notice when money feels stressful, when purchases are exciting, when bills create pressure, and when families make sacrifices. These early lessons can shape how young people handle money later in life.
Across the Black community, financial literacy matters because money knowledge can help families build stronger futures. Many adults were never taught clearly how budgeting, credit, saving, debt, banking, investing, insurance, taxes, or business ownership work. Some had to learn through mistakes, emergencies, or painful experiences. Teaching children and teens earlier gives them a better foundation. It helps them understand that money is not only something to spend. It is a tool for responsibility, opportunity, stability, generosity, and long-term planning.
Financial literacy should not be taught through fear or shame. Young people should not be made to feel guilty for wanting nice things, enjoying small purchases, or dreaming big. Instead, they need guidance that helps them understand choices. They need to learn the difference between needs and wants, short-term pleasure and long-term goals, borrowing and owning, saving and wasting, working and earning, and spending and investing. These lessons can be taught with patience in everyday life.
Families do not need to be wealthy to teach financial literacy. In fact, some of the strongest lessons come from ordinary routines: grocery shopping, comparing prices, saving for a goal, planning a birthday budget, discussing school supplies, helping with a small business idea, or talking honestly about bills in an age-appropriate way. When youth learn how money works, they become more confident and better prepared for adulthood.
1. Money Conversations Should Begin Early.
Children begin learning about money long before they have bank accounts or jobs. They see adults use cash, cards, phones, and online payments. They ask for toys, snacks, clothes, games, and activities. They may not understand where money comes from or why families cannot buy everything immediately. This is why early money conversations matter.
Parents and caregivers can explain money in simple ways. Young children can learn that money is earned through work, used to buy needs, saved for future goals, and shared to help others. They can learn that families make choices because money has limits. These lessons do not need to be heavy or stressful. They can be part of normal conversation.
For example, during grocery shopping, an adult might say, “We are choosing what fits our list today,” or “This one costs less, so we can save money for something else.” During a toy request, a parent might say, “That is something we can save for.” These small moments help children connect money to planning.
Starting early helps money feel less mysterious. Children who grow up hearing healthy money conversations may become more comfortable asking questions and making thoughtful choices as they get older.
2. Youth Need To Understand Needs And Wants.
One of the first financial lessons children should learn is the difference between needs and wants. Needs are things required for daily life, such as food, housing, clothing, transportation, basic school supplies, and healthcare. Wants are things that may be enjoyable but are not always necessary, such as extra toys, trendy clothes, games, expensive snacks, or entertainment.
This lesson is not meant to make children feel bad for wanting things. Wanting things is normal. The goal is to help young people understand priorities. A family may choose to pay bills, buy groceries, or save for school needs before spending on extras. Children who understand this may become more patient and less confused when adults say no.
Teens especially need this lesson because peer pressure and social media can make wants feel like needs. A teen may feel that they must have certain shoes, phones, hairstyles, brands, or experiences to be accepted. Families can talk honestly about the difference between personal style and financial pressure.
Learning needs and wants helps youth build self-control. They begin to understand that every purchase is a choice, and every choice affects what money is available later.
3. Budgeting Teaches Youth How To Plan.
A budget is simply a plan for money. Many young people think budgeting is only for adults, but children and teens can learn the basics early. Budgeting teaches them to decide where money should go before it disappears. It helps them understand spending, saving, giving, and planning.
A child can practice budgeting with allowance, birthday money, small earnings, or gift money. A teen can practice with part-time job income, school expenses, transportation needs, or savings goals. The amount does not have to be large. The habit matters more than the size of the money.
Families can teach a simple budget system. Some money can be used now, some can be saved, and some can be set aside for giving or future goals. Older teens can learn to track spending, compare income to expenses, and plan ahead for larger purchases.
Budgeting helps youth feel more in control. Instead of wondering where their money went, they can see their choices clearly. This builds confidence and responsibility.
4. Saving Builds Patience And Confidence.
Saving money teaches young people patience. In a world of instant purchases and quick online shopping, children and teens need to learn that waiting can be wise. Saving for something meaningful helps them understand delayed gratification and the satisfaction of reaching a goal.
A child might save for a toy, bike, book, game, or special outing. A teen might save for clothes, a phone, a car, college expenses, business supplies, or emergency money. When youth save toward a goal, they learn that small amounts can grow over time.
Families can make saving visible. Younger children may use jars or envelopes. Older youth may use a savings account or digital tracker. Seeing progress can motivate them. A parent can say, “You are closer than last week,” or “Your choices are helping you reach your goal.”
Saving also builds confidence because youth learn they are capable of planning ahead. They begin to see themselves as people who can make disciplined choices. That belief can support many areas of life.
5. Smart Spending Helps Youth Avoid Pressure.
Young people face pressure to spend. Friends, ads, influencers, games, social media, and trends all encourage buying. A child may want the snack everyone has. A teen may want the brand that gets attention. Online games may push in-game purchases. Social media may make expensive lifestyles look normal. Financial literacy helps youth pause before spending.
Smart spending means asking questions before buying. Do I really want this? Will I still care about it next week? Is there a better price? Am I buying this because I like it or because I feel pressured? What will I not be able to buy if I spend this money now? These questions help youth think instead of react.
Families can model smart spending by comparing prices, waiting before big purchases, using lists, and talking about value. Children should see that wise spending is not the same as never buying anything enjoyable. It means choosing with purpose.
When youth learn to resist pressure, they gain confidence. They understand that they do not have to follow every trend to have worth. Their value is not based on what they own.
6. Youth Should Learn How Work Connects To Money.
Children and teens need to understand that money usually comes through work, effort, skill, service, business, or investment. This helps them respect money and the people who earn it. When youth understand the effort behind income, they may become more thoughtful about spending.
Families can explain work in age-appropriate ways. A parent might say, “I work to help pay for our home, food, and needs.” A caregiver might explain how different jobs serve the community. A business owner might show how customers, costs, and profit work. These conversations help youth connect money to responsibility.
Teens can benefit from safe work experiences, internships, volunteering, family business help, or small earning opportunities. They can learn time management, customer service, communication, and professionalism. These skills matter even more than the paycheck.
Understanding work also helps youth think about future careers. They begin asking what skills they need, what education may help, and how they can use their gifts to earn and serve.
7. Entrepreneurship Can Teach Powerful Money Lessons.
Many young people have business ideas. They may want to sell snacks, create art, design clothes, cut grass, braid hair, make jewelry, tutor younger children, edit videos, bake treats, or offer digital services. Youth entrepreneurship can be a powerful way to teach money skills.
A small business idea helps youth learn about costs, pricing, profit, quality, customer service, marketing, and responsibility. They learn that earning money takes planning and effort. They also learn that not every idea works immediately, and mistakes are part of growth.
Families can support youth entrepreneurship safely. Adults can help with supervision, budgeting, supplies, transportation, online boundaries, and customer communication. The goal is to encourage creativity while teaching responsibility.
Entrepreneurship also builds confidence. A young person who earns money from a skill may begin to see their gifts differently. They learn that their ideas can create value. That lesson can last a lifetime.
8. Credit Should Be Explained Before Youth Need It.
Many young adults enter adulthood without understanding credit. They may receive credit card offers, take loans, finance cars, or sign agreements without knowing how interest, payment history, debt, and credit scores work. Families can help by explaining credit before youth are pressured to use it.
Teens should understand that credit is borrowed money that must be repaid. They should know that paying late can hurt future opportunities, while responsible use can help build a stronger financial record. They should also understand that credit cards are not extra income. They are financial tools that can become dangerous when misused.
Families can discuss real examples. A car loan, student loan, credit card, apartment application, or phone plan can become a teaching moment. Young people should know that credit affects more than shopping. It can affect housing, transportation, business opportunities, and financial stress.
Credit education helps protect youth from costly mistakes. It gives them language and awareness before they face adult financial decisions.
9. Giving Teaches Money With Purpose.
Financial literacy is not only about keeping money. It is also about using money with purpose. Giving teaches children that money can help others and support community needs. Families may give through church, charity, family support, community drives, school events, mutual aid, or helping a neighbor.
Children can learn that generosity is part of financial responsibility. This does not mean giving beyond what the family can afford. It means understanding that money can be used to care for others when possible. Even small giving can teach compassion.
Families can include children in giving decisions. A child might help choose canned goods for a food drive, donate part of allowance, or help buy supplies for a community event. Teens can volunteer and see how financial support connects to service.
Giving helps youth avoid seeing money only through selfish desire. It teaches that financial strength can also serve family and community.
10. Family Money Talks Should Be Honest But Age-Appropriate.
Some adults avoid talking about money with children because they do not want to worry them. That instinct can be protective, but complete silence can leave children confused. Youth need honest, age-appropriate money conversations that teach without placing adult burdens on them.
A young child does not need to know every bill or financial stress. But they can understand that the family has a budget. A teen can understand more about expenses, saving, debt, and planning. The key is sharing enough to teach responsibility without making children feel responsible for adult problems.
Parents can say, “We are choosing carefully this month,” or “We are saving for something important,” or “That purchase is not in the budget right now.” These statements are honest without being frightening.
Healthy money conversations reduce shame. They help youth understand that financial planning is normal and that asking questions is okay. Silence teaches nothing, but calm conversation builds wisdom.
11. Financial Mistakes Can Become Lessons.
Young people will make money mistakes. They may spend too quickly, lose money, buy something low quality, forget to save, or regret a purchase. These mistakes can be frustrating, but they can also become learning opportunities.
Adults should avoid using shame as the main teacher. Instead of saying, “You are terrible with money,” they can ask, “What did you learn from this?” or “What would you do differently next time?” This helps youth reflect and grow.
Small mistakes during childhood and teen years can prevent larger mistakes in adulthood. A child who spends all birthday money immediately may learn the importance of saving. A teen who wastes earnings on something unimportant may learn to plan better next time.
Financial confidence grows when youth learn that mistakes are not the end. They are part of becoming wiser. The goal is not perfection. The goal is growth.
12. Financial Literacy Builds A Stronger Future.
Financial literacy helps youth build a stronger future because it gives them tools for adulthood. A young person who understands budgeting, saving, spending, work, credit, giving, and planning is better prepared for college, trade school, jobs, business, family life, and personal goals.
Across the Black community, teaching financial literacy is part of building generational strength. When youth learn money skills early, they can make better decisions, avoid some harmful debt, build confidence, and create more opportunities. These lessons can also be passed down to the next generation.
Families, schools, churches, mentors, youth programs, and local businesses can all support financial education. A community that teaches money wisdom helps children see that financial confidence is possible.
Strong financial futures begin with small lessons. A budget conversation, a savings jar, a grocery store lesson, a youth business idea, or a talk about credit can plant seeds that grow for years.
Conclusion.
Financial literacy helps youth across the Black community build confidence because it teaches them how to understand money, make better choices, plan for goals, and prepare for adulthood. Children and teens need to learn that money is not only for spending. It is also for saving, giving, investing in goals, supporting family needs, and building stability.
Families do not need wealth to teach money wisdom. They can begin with everyday moments such as shopping, saving, budgeting, comparing prices, discussing needs and wants, or encouraging youth entrepreneurship. These lessons help young people develop discipline and confidence over time.
When youth understand money earlier, they are more prepared to handle responsibility later. Financial literacy gives them language, awareness, and practical tools for building stronger futures.
Akukulu Family encourages parents, caregivers, mentors, educators, business owners, and community members to teach one money lesson this month. Talk about saving, help a teen create a budget, explain needs and wants, support a youth business idea, or discuss credit before it is needed. One financial conversation can help a young person build confidence for life.
